
A healthy 35-year-old woman pays about $37 a month for a $500,000, 20-year term policy, and a man about $47, according to MoneyGeek’s 2026 rate analysis.
Quick answer: Term life insurance quotes estimate what you’ll pay for coverage lasting 10 to 30 years, based on your age, gender, health, tobacco use, coverage amount, and term length. You can compare free quotes online in minutes, but your final price is set only after the insurer underwrites your application.
How to Get Instant Online Term Life Insurance Quotes
Online term life insurance quotes come from rate engines that run your basic details through each insurer’s published rate tables and return estimated monthly prices side by side. The quote assumes a health class you expect to qualify for; the insurer confirms your actual class and price during underwriting.
How quote engines work
When you request term life insurance quotes online, the tool matches your age, gender, state, coverage amount, term length, and expected health class against each carrier’s current rates. Independent agencies and brokers can show several insurers at once, while a single insurer’s website shows only its own price. Because each company weighs age and health differently, the cheapest carrier for one person is often not the cheapest for another.
What information you need for an accurate quote
• Date of birth and gender
• Height and weight
• Tobacco or nicotine use in the last 12 months or longer
• Major health conditions and current prescriptions
• Family history of early heart disease or cancer
• Coverage amount and term length you want
• State of residence
The more honest and complete your answers, the closer your quote will be to your final premium. Estimating your health class too optimistically is the most common reason a final offer comes back higher than the quote.
Note: Free term life insurance quotes don’t require a hard credit inquiry and don’t affect your credit score. Most quotes stay valid for about 30 days, and some insurers honor them for up to 90 days, according to MoneyGeek.
Average Cost Breakdown: How Much Do Term Life Quotes Cost?
For healthy nonsmokers in their 20s and 30s, term life insurance quotes typically run about $10 to $25 a month for $100,000, $25 to $80 for $500,000, and $40 to $120 for $1 million, depending on term length. Prices rise slowly through the 30s, then climb steeply after 45.
Key cost factors
• Coverage amount: larger policies cost more, but the price per $1,000 of coverage usually falls as the amount rises.
• Term length: a 30-year term costs more per month than a 10-year term because it covers older ages.
• Age: the biggest single driver; every birthday raises the price.
• Health risk class: insurers place you in a class such as Preferred Plus, Preferred, Standard Plus, or Standard based on your health and history.
• Tobacco use: smokers often pay three times or more what nonsmokers pay.
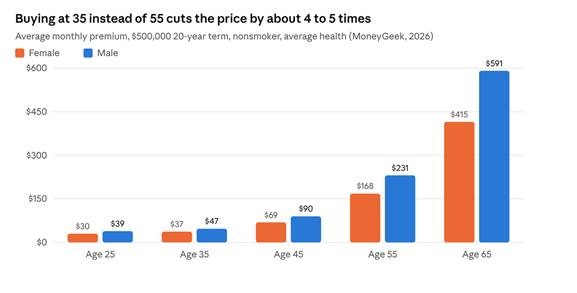
MoneyGeek 2026 average rates, $500,000 20-year term
Table 1: $100,000 level term monthly cost
| Age | Gender | 10-year term | 20-year term | 30-year term |
| 25 | Female | $10 | $12 | $17 |
| 25 | Male | $12 | $14 | $20 |
| 35 | Female | $12 | $14 | $21 |
| 35 | Male | $14 | $16 | $25 |
| 45 | Female | $17 | $21 | $36 |
| 45 | Male | $20 | $26 | $45 |
| 55 | Female | $32 | $45 | $72 |
| 55 | Male | $41 | $60 | $94 |
| 65 | Female | $73 | $103 | Not available |
| 65 | Male | $101 | $141 | Not available |
Source: MoneyGeek, updated October 2, 2026.
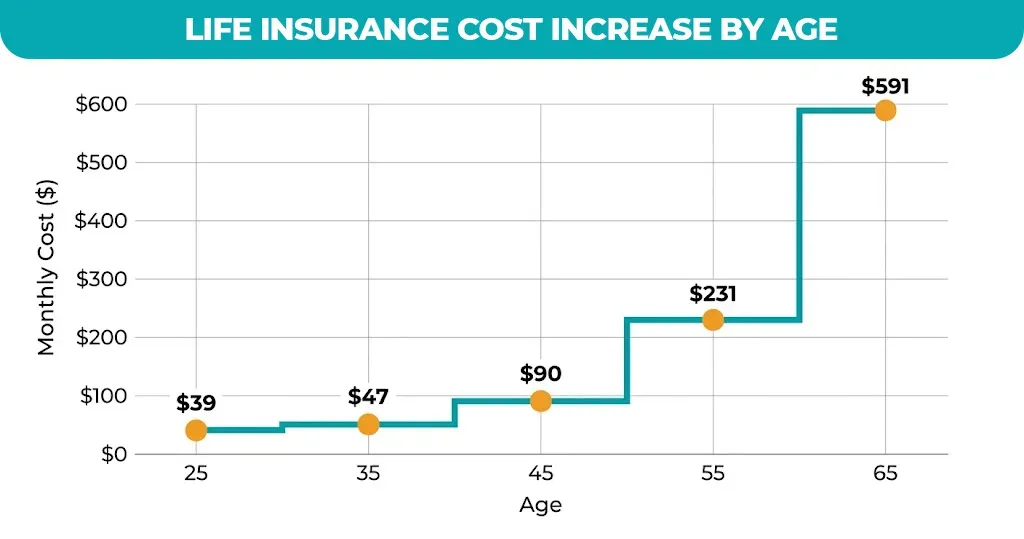
Table 2: $500,000 level term monthly cost
| Age | Gender | 10-year term | 20-year term | 30-year term |
| 25 | Female | $25 | $30 | $51 |
| 25 | Male | $31 | $39 | $63 |
| 35 | Female | $28 | $37 | $65 |
| 35 | Male | $34 | $47 | $80 |
| 45 | Female | $49 | $69 | $123 |
| 45 | Male | $61 | $90 | $159 |
| 55 | Female | $104 | $168 | $283 |
| 55 | Male | $144 | $231 | $372 |
| 65 | Female | $262 | $415 | Not available |
| 65 | Male | $385 | $591 | Not available |
Source: MoneyGeek, updated September 22, 2026.
Table 3: $1,000,000 level term monthly cost
| Age | Gender | 10-year term | 20-year term | 30-year term |
| 20 | Female | $39 | $51 | $81 |
| 20 | Male | $51 | $64 | $110 |
| 30 | Female | $40 | $54 | $95 |
| 30 | Male | $51 | $67 | $119 |
| 40 | Female | $60 | $86 | $154 |
| 40 | Male | $74 | $109 | $198 |
| 50 | Female | $130 | $194 | $371 |
| 50 | Male | $171 | $262 | $515 |
| 60 | Female | $301 | $545 | Not available |
| 60 | Male | $429 | $771 | Not available |
Source: MoneyGeek, updated September 30, 2026; published by decade of age. All rates are averages for nonsmokers in average health. Applicants who qualify for Preferred Plus often pay less, and Standard or tobacco classes pay more. Premier Services Agency’s term life insurance rates guide covers more pricing detail.
Comparing Term Life Quotes: Level Term vs. Decreasing vs. Brand Plans
Most term life insurance quotes you see online are for level term: the premium and death benefit stay the same for the whole term. Decreasing term and some brand-name plans work differently, so compare the structure, not just the starting price.
Level term life insurance quotes
Level term locks a fixed premium and a fixed death benefit for 10, 15, 20, 25, or 30 years, and some insurers offer up to 40. That level premium guarantee is what makes term easy to budget for. Premier Services Agency explains the details in level term life insurance.
| Type | Premium | Death benefit | Best for |
| Level term | Fixed for the term | Fixed | Income replacement, family protection |
| Decreasing term | Usually fixed | Shrinks over time | Matching a mortgage or loan balance |
| Annual renewable term | Rises every year | Fixed | Very short-term needs |
| Age-banded group term (such as AARP) | Rises at each five-year age band | Fixed | Seniors wanting simple, smaller coverage |
Evaluating brand options: AARP, Progressive, and independent brokers
AARP term life insurance quotes come from New York Life, which issues the only life insurance AARP endorses. The AARP Level Benefit Term plan is for members ages 50 to 74, offers modest coverage amounts (NerdWallet reports $10,000 to $150,000), and ends at age 80. Despite the name, premiums rise each time you enter a new five-year age band, per the AARP program FAQ, so compare it carefully against a traditional 10- or 20-year level term.
Progressive term life insurance quotes come through Progressive’s life insurance marketplace. Progressive refers shoppers to partner carriers through eFinancial, and it has also begun issuing its own term policies through Progressive Life Insurance Company in some states, as reported by S&P Global.
Independent agencies and brokers can quote several insurers at once. That matters because, for the same 40-year-old buying $100,000 of 20-year term, MoneyGeek found the cheapest carrier charged less than half what the most expensive one did.
No Medical Exam Term Life Insurance Quotes
Healthy applicants can often get term life insurance without a medical exam through accelerated underwriting, which replaces blood and urine tests with database checks and can deliver a decision within days. For qualified buyers in their 30s and 40s, no-exam term life insurance quotes now cost only slightly more than fully underwritten coverage.
Instant approval and accelerated underwriting
Instead of a paramedical exam, the insurer pulls third-party data to verify your application:
• Prescription history: pharmacy databases show medications you’ve filled.
• MIB report: the MIB (Medical Information Bureau) flags conditions disclosed on past insurance applications.
• Motor vehicle record (MVR): shows DUIs, suspensions, and moving violations.
• Medical and credit-based data: some insurers also review electronic health records and credit history.
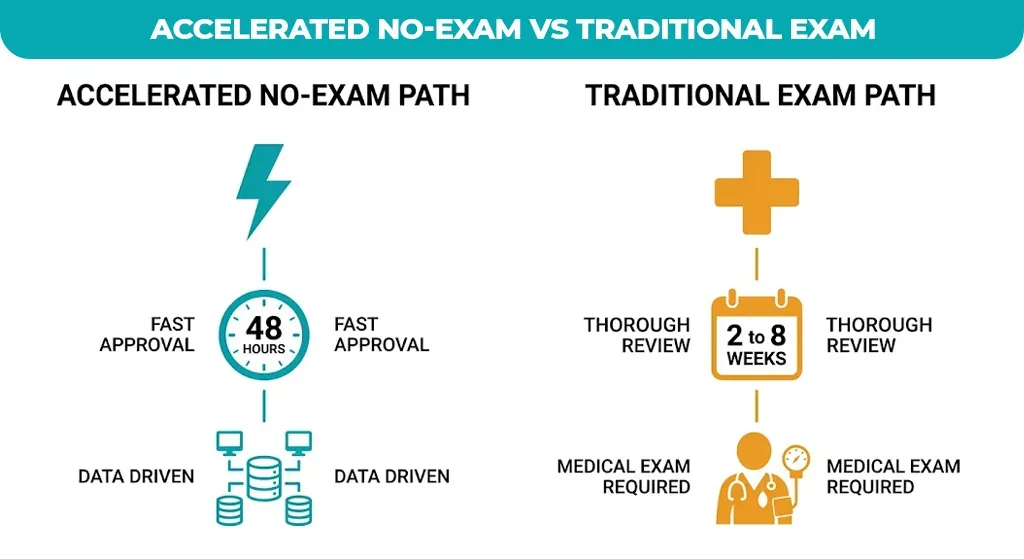
If everything lines up, many insurers approve within 48 hours; fully underwritten policies typically take two to eight weeks, according to MoneyGeek. If the data raises questions, the insurer can still require an exam.
Medical exam vs. no-exam quotes: is there still a price penalty?
| Profile, 20-year term | With medical exam | Without exam | Difference |
| $1M, female, 40 | $86 | $91 | +$5 |
| $1M, male, 40 | $109 | $116 | +$7 |
| $1M, female, 60 | $545 | $565 | +$20 |
| $1M, male, 60 | $771 | $806 | +$35 |
Average monthly rates from MoneyGeek. The gap is small for younger buyers and widens with age; across its $500,000 analysis, MoneyGeek found no-exam coverage cost about 10% to 20% more.
Who qualifies best for instant no-exam coverage?
• Adults roughly 18 to 60 with no major health conditions
• Nonsmokers with a healthy build and normal blood pressure
• A clean driving record and no hazardous hobbies
• Coverage amounts within the insurer’s no-exam limit, often up to $1 million to $3 million
If you have health conditions, a medical exam can actually earn you a better rate by proving your health is well managed. Premier Services Agency covers the options in life insurance with no medical exam and simplified issue life insurance.
Specialized Term Life Quotes for Different Demographics
The same rate tables apply to everyone, but what you should buy changes with your situation. Families usually need large coverage for both parents, women pay noticeably less than men, and seniors face fewer term options and higher prices.
Family term life insurance quotes
In a two-income household, each spouse usually needs a separate policy sized to the income and obligations that would disappear if they died. A stay-at-home parent needs coverage too: childcare, housekeeping, and transportation would cost real money to replace. Many families buy one 20- or 30-year term policy on each parent and add a child rider for small coverage on children. Premier Services Agency’s family life insurance plans guide covers the options.
Term life insurance quotes for women
Women pay less because they live longer on average. In MoneyGeek’s 2026 data for a $500,000, 20-year policy, women pay about 20% to 30% less than men at the same age:
| Age | Female | Male | Women pay less by |
| 25 | $30 | $39 | 23% |
| 35 | $37 | $47 | 21% |
| 45 | $69 | $90 | 23% |
| 55 | $168 | $231 | 27% |
| 65 | $415 | $591 | 30% |
Because rates rise with age for everyone, buying earlier locks in the lower price for the full term.
Term life insurance quotes for seniors
After 60, term options narrow: 30-year terms generally disappear, and 20-year terms are often unavailable past about 65. A 10-year level term is usually the most practical choice, covering a remaining mortgage or a spouse’s income until retirement savings take over. MoneyGeek’s 2026 averages for $100,000 of 10-year term are $73 a month for women and $101 for men at 65, rising to $104 and $150 at 70.
If you mainly need to cover funeral costs, a small final expense or guaranteed issue policy may fit better. A $15,000 guaranteed issue policy averages about $90 a month for a 65-year-old woman and $116 for a man, per MoneyGeek, with a two-year graded death benefit. Premier Services Agency compares the choices in term life insurance for seniors and final expense insurance for seniors.
How to Calculate Your Coverage Needs
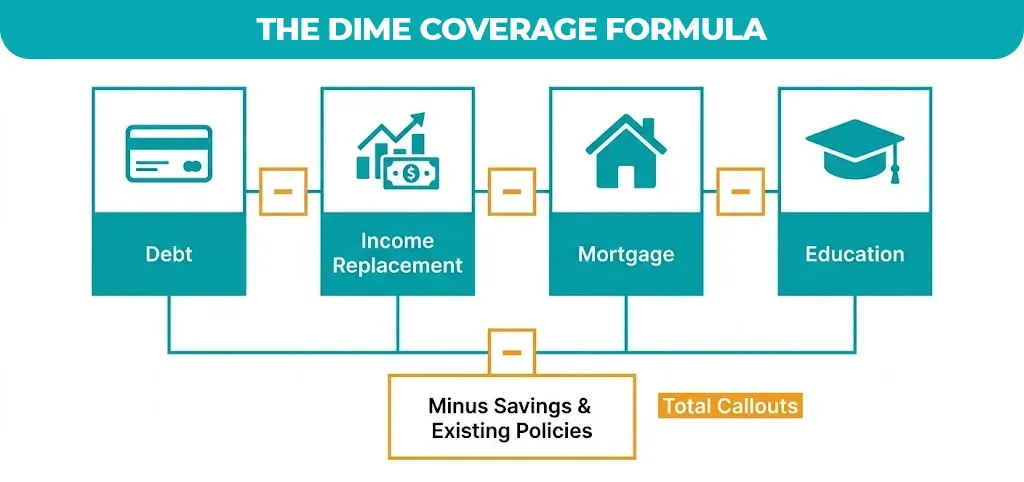
Before comparing term life insurance quotes, decide how much coverage you need and for how long. The DIME formula adds up your debts, income replacement, mortgage, and education costs; your term length should last until the biggest of those obligations ends.
The DIME formula
Coverage=Debt+IncomeYears+Mortgage+Education-Savings and existing coverage
| DIME item | What to include | Example family |
| Debt | Car loans, credit cards, personal loans, final expenses | $35,000 |
| Income | Annual income times years your family would need it (10 is a common rule) | $65,000 × 10 = $650,000 |
| Mortgage | Remaining balance | $240,000 |
| Education | Expected college costs for each child | $90,000 |
| Minus savings and existing coverage | Emergency fund, group life from work | −$75,000 |
| Coverage need | $940,000 |
The example figures are illustrative. In this case, a $1 million policy would be a sensible round number.
Choosing the right duration
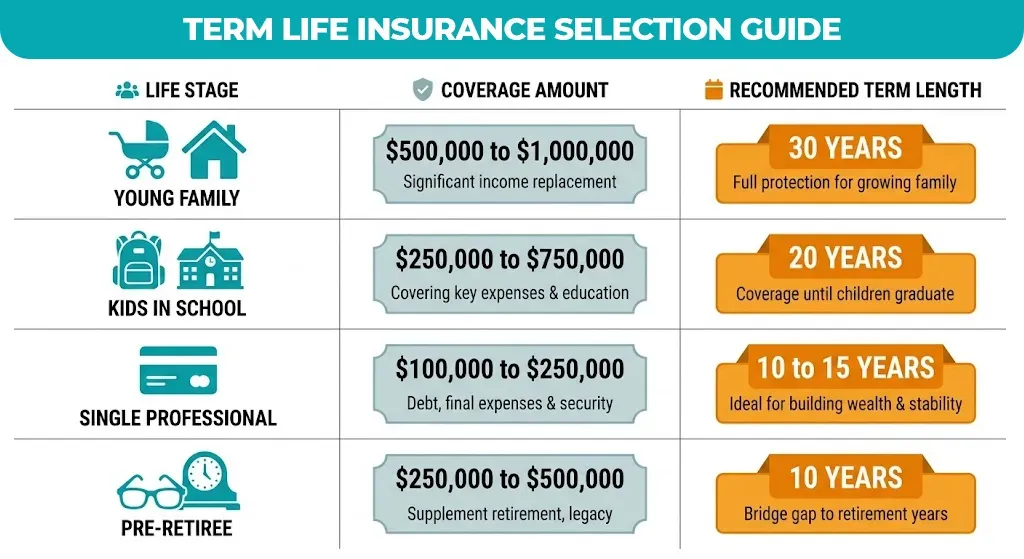
| If your longest obligation is… | Consider |
| A loan or need ending within about 10 years | 10-year term |
| Children who are already in school | 15- or 20-year term |
| A newborn, toddler, or new 30-year mortgage | 30-year term |
| Income replacement until retirement | Term ending at your planned retirement age |
Buying one longer term is often cheaper than stacking short ones. MoneyGeek’s example: a 40-year-old woman pays $26 a month for a 30-year, $100,000 policy, about $9,360 over 30 years, versus about $10,080 for three back-to-back 10-year policies bought at 40, 50, and 60, and that assumes she stays healthy enough to qualify each time. Premier Services Agency compares lengths in its 10-year and 30-year term life insurance guides.
How to Lock In the Cheapest and Best Term Life Insurance Rates
The cheapest term life insurance quotes go to people who apply young, qualify for a top health class, pay annually, and compare several insurers. Small steps before you apply can move you up a risk class and save hundreds of dollars a year for the entire term.
Proactive health steps before you apply
• Quit nicotine: most insurers reclassify former smokers after 12 months, which can cut premiums by more than half at older ages, per MoneyGeek.
• Manage blood pressure and cholesterol: take prescribed medication consistently and bring recent readings.
• Work on BMI: even modest weight loss can move you into a better build category.
• Prepare for the exam: fast for 8 to 12 hours if instructed, skip alcohol and hard workouts the day before, and schedule it in the morning.
• Apply sooner: each year you wait raises the base price, and a new diagnosis can raise it far more.
Annual vs. monthly premium payments
Paying once a year is usually cheaper than paying monthly because insurers add a small charge for installment billing. Policygenius notes that annual payment can save up to about 5%; the exact modal factor varies by insurer, so ask for both prices.
| Payment mode | How it works | Cost effect |
| Annual | One payment per year | Lowest total cost |
| Semi-annual | Two payments per year | Slightly higher |
| Monthly (bank draft) | Twelve automatic payments | Highest total cost, easiest on cash flow |
Independent broker agency vs. captive insurer
A captive agent represents one insurance company and can only quote its products. An independent agency can compare several carriers and steer you toward the one that prices your age and health most favorably, which matters because carrier prices for identical coverage can differ widely.
Note: Compare quotes on the same coverage amount, term length, and health class. A quote that looks cheaper because it assumes Preferred Plus can end up more expensive than a competitor once you’re underwritten as Standard. Premier Services Agency explains how the major carriers compare in top-rated life insurance companies.
Conclusion:
Term life insurance is the most affordable way to protect your family, and comparing quotes is the easiest way to keep it affordable. Prices for identical coverage can differ by more than half between insurers, so a few minutes of comparison can save thousands over a 20- or 30-year term. Lock in your rate while you’re young and healthy, match the term to your longest obligation, and make sure the quote reflects the health class you’ll actually get.
| Your situation | Good starting quote |
| Young family with a new mortgage | $500,000 to $1M, 30-year level term |
| Kids in school, mortgage half paid | $500,000, 20-year level term |
| Single, with debts or co-signed loans | $100,000 to $250,000, 10- or 20-year term |
| Age 60+ covering a spouse or loan | $100,000+, 10-year level term |
| Mainly funeral costs | Final expense or guaranteed issue coverage |
Get Your Free Term Life Insurance Quote From Premier Services Agency
Premier Services Agency helps families and seniors find affordable life insurance, including term life, with plain-language guidance and a no-pressure process.
• Free, no-obligation quotes for term and permanent coverage.
• More than 20 years of experience helping families choose coverage.
• A simple application with no confusing paperwork.
• Ongoing support for policy questions and claims.