
What Is Final Expense Life Insurance?
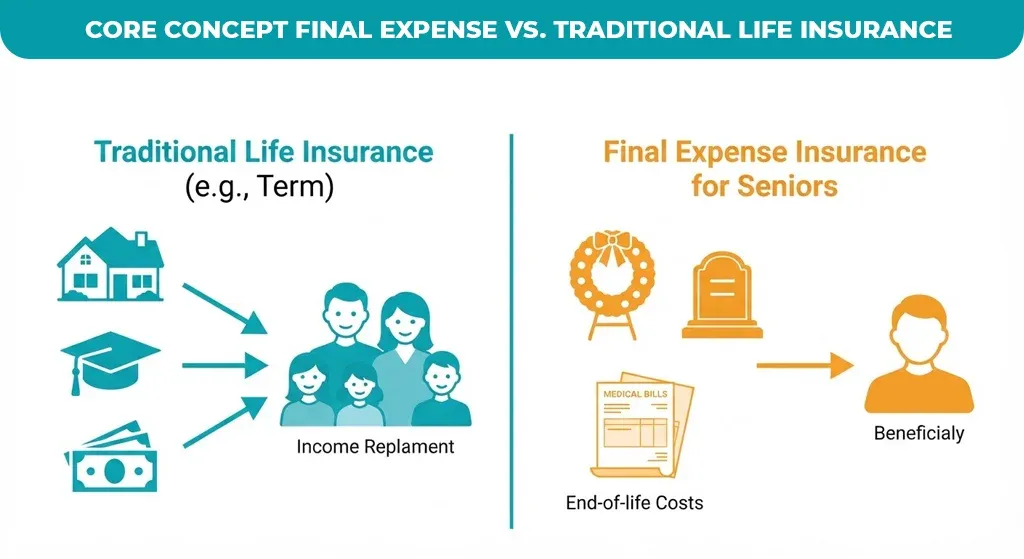
Final expense life insurance for seniors is a category of permanent whole life insurance created specifically to pay for the costs that follow a death: the funeral, the burial or cremation, and any medical or legal bills left behind. It is also commonly called burial insurance or simplified issue life insurance, and it works very differently from the term life policies many people carried during their working years.
Traditional life insurance is usually built around replacing lost income, paying off a mortgage, or funding a spouse’s living expenses for decades. Final expense insurance for seniors has a narrower, more practical job. It exists to make sure a funeral bill, a cemetery fee, or a stack of medical invoices never becomes a burden for the family left behind. Because the coverage amount is small compared with a standard policy, the underwriting is faster, and the health requirements are far less strict, which is why so many people search specifically for final expenses insurance for seniors rather than a full term or whole life policy.
What Is a Final Expense Life Insurance Policy?
A final expense insurance policy for seniors is a contract between you and an insurance company. You pay a fixed monthly premium, and in exchange, the insurer promises to pay a tax-free lump sum, usually between $5,000 and $25,000, to your named beneficiary when you pass away. That beneficiary can spend the money however they choose; nothing requires it to go toward the funeral specifically, though most families use it exactly for that.
There are two common structures you will run into when comparing a policy:
- Simplified issue policies ask a short list of health questions but skip the medical exam. Approval is often decided within a few days, and premiums tend to be lower because the insurer has some information about your health.
- Guaranteed issue policies skip health questions entirely. Anyone within the eligible age range is approved automatically, which makes this structure popular among people searching for the best final expense life insurance for seniors with serious pre-existing conditions. The trade-off is a higher premium and, typically, a two-year graded waiting period before the full death benefit applies.
Choosing Between the Two
What Are the Benefits of Final Expense Insurance?
The appeal of final expense insurance for seniors comes down to accessibility and certainty. Here are the advantages that matter most:
- No medical exam for most plans. Approval is based on a short questionnaire or, with guaranteed issue coverage, on nothing but your age.
- Fast approval. Many applications are approved within a few business days rather than the weeks a full underwriting process can take.
- Fixed premiums for life. Your rate is set the day your policy is issued and cannot rise later, even if your health changes.
- Permanent coverage. As long as premiums are paid, a final expense whole life insurance policy for seniors never expires and never needs to be renewed.
- Fast, flexible, tax-free payout. Funds are typically released to the beneficiary within one to two days of a claim being filed, and can be used for anything, not just funeral costs.
- Available at older ages. Because coverage amounts are small, insurers can extend final expense insurance for seniors over 80, and even final expense insurance for seniors over 85, in situations where a standard term policy would be declined outright.
What Are the Drawbacks of Final Expense Insurance?
No product is perfect, and final expense insurance for seniors comes with real trade-offs that are worth understanding before you buy.
- Higher cost per thousand dollars of coverage. Because underwriting is simplified or skipped entirely, insurers charge more per dollar of death benefit than they would for a fully underwritten term policy.
- Smaller face values. Most policies cap out between $25,000 and $50,000, which is enough for a funeral and some bills but not a broader financial safety net.
- Waiting periods on guaranteed issue plans. If you pass away from natural causes within the first two years of a guaranteed issue policy, your beneficiary typically receives only a return of premiums paid plus interest, not the full face value.
- Rate does not reward good health. Someone in excellent health often pays close to the same premium as someone with a chronic condition, since simplified and guaranteed issue plans are not priced individually the way fully underwritten policies are.
Weighing these drawbacks against the benefits is the real work of shopping for final expense insurance for seniors, and it is why comparing quotes from several carriers matters so much.
What Does Burial Insurance Cover?
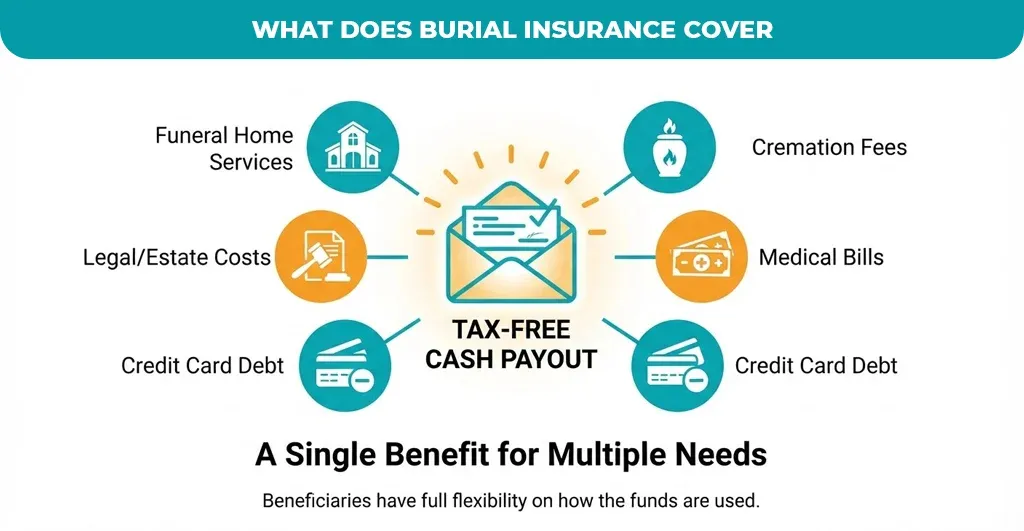
Burial insurance, another name for final expense insurance for seniors, pays a lump-sum death benefit that beneficiaries can use for essentially any purpose. In practice, most families put the money toward:
- Funeral home services and viewing or visitation costs
- Casket, urn, or cremation fees
- Cemetery plot, headstone, and burial charges
- Transportation and clergy or officiant fees
- Outstanding medical bills tied to a final illness
- Credit card balances, small loans, or other short-term debts
- Legal, probate, or estate administration costs
Because the payout is not restricted, final expense burial insurance for seniors is often described as more flexible than a prepaid funeral contract, which only covers services purchased through a specific funeral home. If money is left over after the funeral and related bills are paid, the beneficiary keeps the remainder.
How Much Is Burial Insurance?
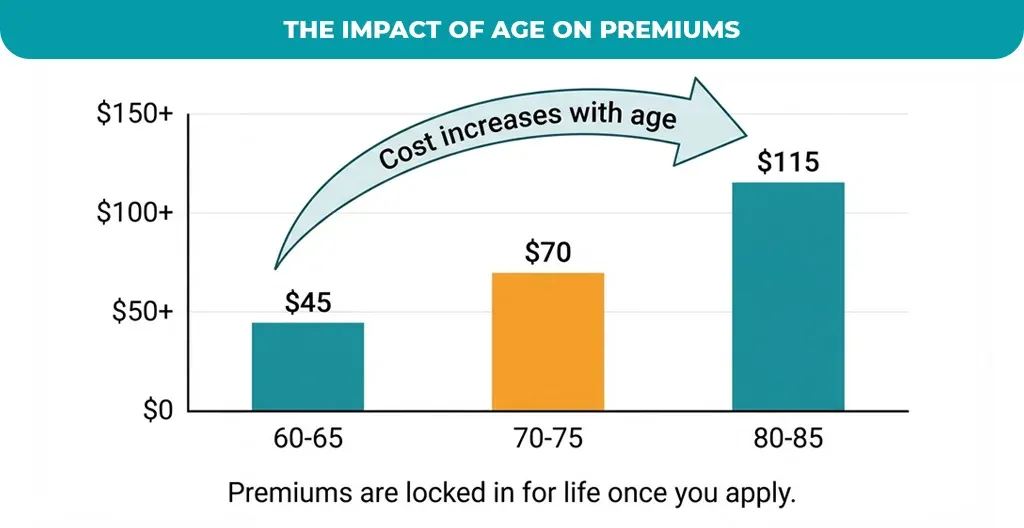
Pricing for final expense insurance for seniors depends mainly on age, gender, coverage amount, tobacco use, and health classification. As a general guide, a $10,000 policy tends to run:
- Ages 60 to 65: roughly $35 to $55 per month
- Ages 70 to 75: roughly $55 to $85 per month
- Ages 80 to 85: roughly $90 to $140 per month
These figures are national averages, not quotes, and actual pricing will vary by carrier, state, and underwriting class. Smokers usually pay one and a half to two times more than non-smokers for the same coverage, and women often receive slightly lower rates than men at the same age due to longer average life expectancy. Because the premium is locked in at enrollment, applying today rather than in five years is typically the biggest single factor in keeping final expense insurance for seniors affordable over the life of the policy.
How To Buy a Final Expense Policy
Buying final expense insurance for seniors does not need to be complicated if you follow a straightforward process.
- Decide how much coverage you actually need. Add up an estimated funeral cost in your area plus any medical or legal bills you want covered, then work backward to a face value, typically between $10,000 and $20,000 for most families.
- Compare simplified issue and guaranteed issue options. If you are in reasonably good health, a simplified issue policy will almost always be cheaper. If you have been declined elsewhere, guaranteed issue removes the health barrier entirely.
- Get quotes from more than one carrier. Pricing among the best final expense insurance companies for seniors can vary significantly for identical coverage, so comparing two or three quotes is worth the extra ten minutes.
- Read the fine print before you sign. What looks like the best final expense insurance policy for senior applicants on paper can still include a graded waiting period, so confirm the details in writing.
- Check the carrier’s financial strength rating. Look for an AM Best rating of B+ or higher before committing, since this policy still needs to be solvent decades from now.
- Review the waiting period carefully. Ask directly whether the policy has a graded death benefit and how long the waiting period lasts before signing anything.
- Work with a licensed agent who represents multiple carriers. An independent agent can shop several policies at once instead of pushing a single company’s product.
An agency like Premier Services Agency can walk you through simplified issue and guaranteed issue options side by side, compare carrier ratings, and help you land on a final expense insurance policy for seniors that actually fits your budget, with no pressure and no guesswork.
Conclusion
Final expense insurance exists for one simple reason: to keep a sudden funeral bill from becoming a devastating financial emergency for the people you love. By understanding how a final expense life insurance policy works, weighing the benefits against the drawbacks, and comparing quotes before you buy, you can lock in coverage that protects your family without stretching your monthly budget.
When you are ready to secure your family’s future and ease the future stress of end-of-life expenses, turn to trusted experts who understand your needs. Visit Premier Services Agency today to explore tailored coverage options and receive a personalized quote designed to protect what matters most.