Open Care Life Insurance Review 2026: Cost & Legit?

Open Care Life Insurance, also marketed as Open Care Seniors, is an independent insurance brokerage based in Naples, Florida, not an insurance carrier. It does not underwrite policies, set final premiums, or pay claims itself. Instead, it connects applicants with final expense, guaranteed issue, and term life insurance policies underwritten by other licensed carriers, most notably Mutual of Omaha for the final expense application on its own website.

The company advertises rates “starting at $7.49 per month,” but that figure applies to one specific scenario: $2,000 of coverage for a healthy, non-smoking 50-year-old woman. Most applicants pay considerably more once age, gender, tobacco use, health class, and coverage amount are factored in.

Open Care is a licensed, legitimate agency. It is not accredited by the Better Business Bureau, and there is very little independent customer feedback tied to its name. Below is a breakdown of how its policies work, what they actually cost by age, and how to compare them against direct carriers before you apply.

Quick Answer
Open Care Life Insurance is a licensed brokerage, not an insurer. It sells final expense (whole life) policies from $2,000 to $50,000 and term life up to $1,000,000, mostly issued by Mutual of Omaha. The advertised $7.49-a-month rate applies only to a $2,000 policy for a healthy 50-year-old woman; a typical $8,000 to $10,000 policy runs roughly $20 to $85 a month for applicants in their 50s and 60s, rising for older or guaranteed issue applicants.

Key Takeaways

  • Open Care Life Insurance is a broker, not a carrier; it places applicants with partner insurance companies rather than underwriting coverage itself.
  • The advertised $7.49-a-month rate applies to one narrow applicant profile. Most seniors pay between $17 and $250+ a month depending on age, gender, and coverage amount.
  • Final expense plans range from $2,000 to $50,000 and come in two forms: Simplified Issue (health questions, no waiting period if approved) and Guaranteed Issue (no health questions, two-year graded period).
  • Open Care is not accredited by the Better Business Bureau and carries no independent A.M. Best financial-strength rating, since that rating applies to the underlying carrier, not the broker.
  • Getting quotes from at least two or three sources, and confirming the underwriting carrier in writing, is the most reliable way to know you are getting a competitive rate.

What Is Open Care Life Insurance?

Open Care Life Insurance (Open Care Seniors) is an independent insurance agency, not an insurance company. Based in Naples, Florida, it markets final expense, guaranteed issue, and term life insurance to adults roughly ages 18 to 90, then routes approved applicants to a partner carrier, such as Mutual of Omaha, that actually issues the policy and pays the death benefit.
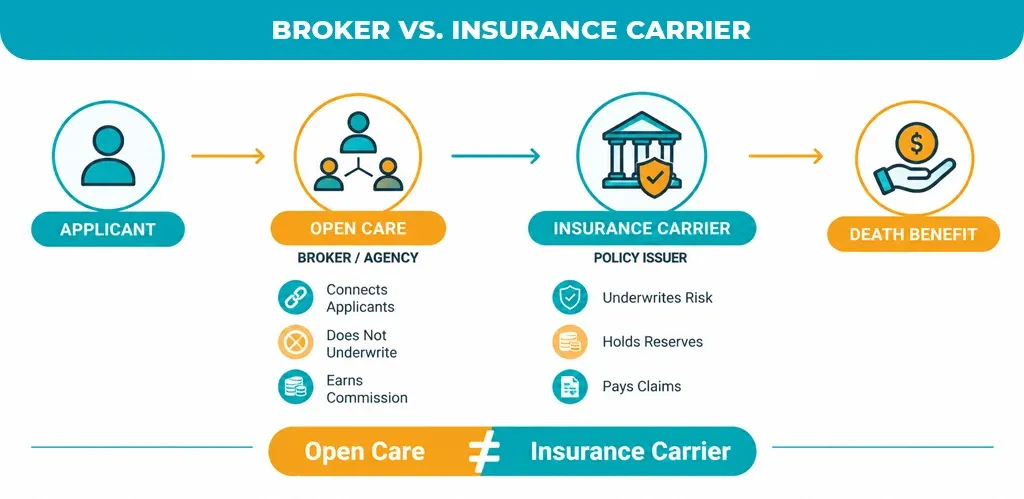
Broker vs. Insurance Carrier

This broker-versus-carrier distinction matters because it changes who is financially responsible for your policy. An insurance carrier is the company that underwrites risk, holds reserves, and pays claims. A broker or agency, by contrast, earns a commission for connecting a buyer with a carrier and generally is not the party that pays out when a policyholder dies. This is a common and legal structure in the senior insurance market; several other well-known “senior life insurance” brands operate the same way.

One point of confusion worth clearing up: a separate, unrelated company also operates under the name “Opencare” as a dental-referral platform based in San Francisco, with its own Better Business Bureau profile. That business has no connection to life insurance and should not be confused with Open Care Life Insurance or Open Care Seniors.

Is Open Care Life Insurance Legit?

Yes. Open Care operates as a licensed insurance agency, and the policies it places come from regulated carriers. However, it is not accredited by the Better Business Bureau, carries no independent A.M. Best financial-strength rating, and has almost no visible customer reviews on Google, Yelp, or Trustpilot under its own name.

Legitimacy and transparency are two different questions. On legitimacy, there is no indication Open Care is operating outside the law; it is a licensed agency selling real insurance products from regulated carriers. On transparency, independent reviewers have raised consistent concerns. One insurance review site that audits customer-service response times and public review counts found zero reviews for Open Care Seniors across the BBB, Trustpilot, Google, and Yelp as of mid-2026, an unusually thin public record for a nationally advertised insurance brand.

It is also worth understanding what an A.M. Best rating does and does not cover. A.M. Best rates the financial strength of insurance carriers, the companies that actually hold reserves and pay claims, not insurance brokers or agencies. Since Open Care is a broker, it would not be expected to carry its own A.M. Best rating regardless of its reputation.

Consumers can also check a carrier’s licensing and complaint history through the National Association of Insurance Commissioners (NAIC), which maintains a public complaint index by company and state. Because Open Care does not disclose its full carrier network upfront, applicants generally cannot run this check until later in the application process.

Stop Guessing With Your Coverage

Before you commit to a final expense policy through Open Care or any broker, get your specific quote in writing and confirm the underwriting carrier.


How Much Does Open Care Life Insurance Cost?

Open Care’s $7.49-a-month headline rate covers only $2,000 of coverage for a healthy, non-smoking 50-year-old woman. For $8,000 of Simplified Issue final expense coverage, the rate chart published on OpenCareSeniors.com shows non-smoking monthly premiums ranging from roughly $17 at age 40 to more than $200 at age 90.

Sample Monthly Rates: $8,000 Final Expense Coverage, Non-Smoker

AgeFemaleMale
40$17$19
50$21$25
60$29$36
70$42$60
80$84$111
90$205$242

A handful of factors move the price up or down from this baseline:

  • Age at application. Final expense premiums are priced to be paid up over your remaining life expectancy, so the older you are when you apply, the higher the monthly cost.
  • Gender and smoking status. Non-smoking women generally receive the lowest rates in this table; smokers of either gender pay meaningfully more at the same age.
  • Health classification. Even on a Simplified Issue plan, your answers to the health questionnaire sort you into a rate class such as preferred, standard, or substandard, which shifts your premium within the published range.
  • Coverage amount. A $25,000 death benefit costs proportionally more per month than the $8,000 or $10,000 examples above at the same age and health class.

The gap between the $7.49 teaser and a real quote is not necessarily deceptive in a legal sense, since the $7.49 rate is genuinely available to that one narrow buyer profile. It is, however, a marketing tactic common across the final expense industry, used to generate phone calls rather than to represent what most callers will actually pay. The safest approach with any “as low as” insurance ad is to request your specific quote in writing before providing payment information.

What Coverage Options Does Open Care Offer?

Open Care sells two main product lines: final expense whole life insurance, which is the focus of its television advertising, and term life insurance, which is available but less heavily marketed.

Final Expense (Whole Life) Insurance

Final expense insurance, also called burial insurance, is a small whole life policy typically ranging from $2,000 to $50,000 in death benefit. It is designed to cover funeral costs, cremation, outstanding medical bills, or small debts rather than to replace income or build significant wealth for heirs. Like other whole life products, premiums are level for life, and the policy accumulates modest cash value over time.
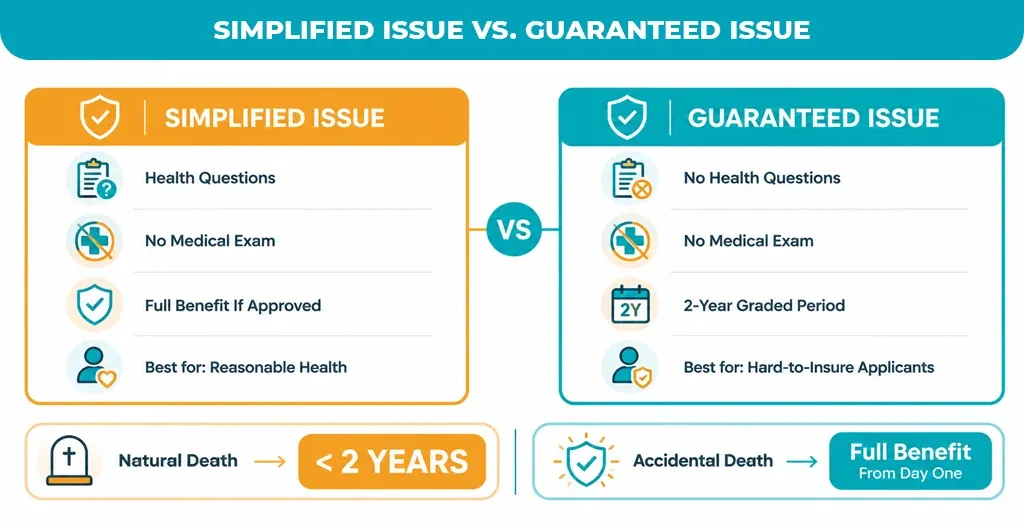
Simplified Issue vs. Guaranteed Issue  

Open Care offers final expense coverage through two underwriting paths:

FeatureSimplified IssueGuaranteed Issue
Medical examNot requiredNot required
Health questionsYes, on an application questionnaireNone
ApprovalBased on health answersAutomatic for eligible ages
Waiting periodNone if approvedTwo years for natural death
Accidental deathCovered from day oneCovered from day one
Best forApplicants in reasonable healthApplicants likely to be declined elsewhere

Under a Guaranteed Issue policy, if the policyholder dies of natural causes within the first 24 months, beneficiaries typically receive only a refund of premiums paid plus a small amount of interest, not the full face amount. Death by accident is generally covered at the full death benefit from the first day of the policy. This graded-benefit structure is standard across the guaranteed acceptance segment of the industry, not unique to Open Care.

Term Life Insurance

Open Care also offers term life insurance in amounts generally ranging from $25,000 up to $500,000 to $1,000,000, in 10-, 20-, or 30-year terms, for applicants up to around age 75. Unlike final expense whole life, term life insurance requires full health underwriting and does not build cash value; it pays a death benefit only if the insured dies during the term. Because full underwriting is required, term coverage is less accessible to many seniors with health conditions, which is likely why it is not the focus of Open Care’s television marketing.

Open Care Life Insurance Reviews and Complaints

Open Care Life Insurance has an unusually thin public review record for a nationally advertised brand. Independent audits have found no reviews under its name on the Better Business Bureau, Trustpilot, Google, or Yelp, and it is not BBB accredited.

This absence of reviews cuts both ways. It means there is little documented evidence of widespread customer complaints, but it also means prospective buyers cannot verify claims processing speed, customer service quality, or renewal experiences through past customers the way they could with a more established carrier or agency. Reviewers have more consistently flagged the volume of follow-up marketing, repeated phone calls, and mailers after a quote request as a recurring complaint theme, rather than claims-related disputes.

If you have already requested a quote and want to verify a specific carrier before signing, the two most useful public resources are the NAIC’s consumer complaint index, which tracks complaint ratios by company and state, and the carrier’s own A.M. Best financial-strength rating, both of which apply to the underwriting insurance company rather than to Open Care itself.

Open Care Life Insurance: Pros and Cons

Pros

Cons

Application can often be completed in a single phone call or online session

Carrier network is not publicly disclosed, so you cannot check the underwriting company’s rating in advance

No medical exam for Simplified Issue or Guaranteed Issue plans

Advertised $7.49 rate applies to one narrow profile and misrepresents typical costs for most applicants

Guaranteed Issue accepts applicants who might be declined elsewhere for health reasons

Very limited independent customer reviews make service quality hard to verify

Access to more than one carrier product through a single point of contact

Not accredited by the Better Business Bureau

How Open Care Compares to Buying Direct

Open Care’s confirmed application partner, Mutual of Omaha, is one of the more established names in the final expense market, which is a point in Open Care’s favor. But because Open Care does not disclose its full carrier list, an applicant cannot know in advance whether they are being routed to the most competitively priced option among Open Care’s partners, or simply to whichever carrier pays the highest commission on that application.
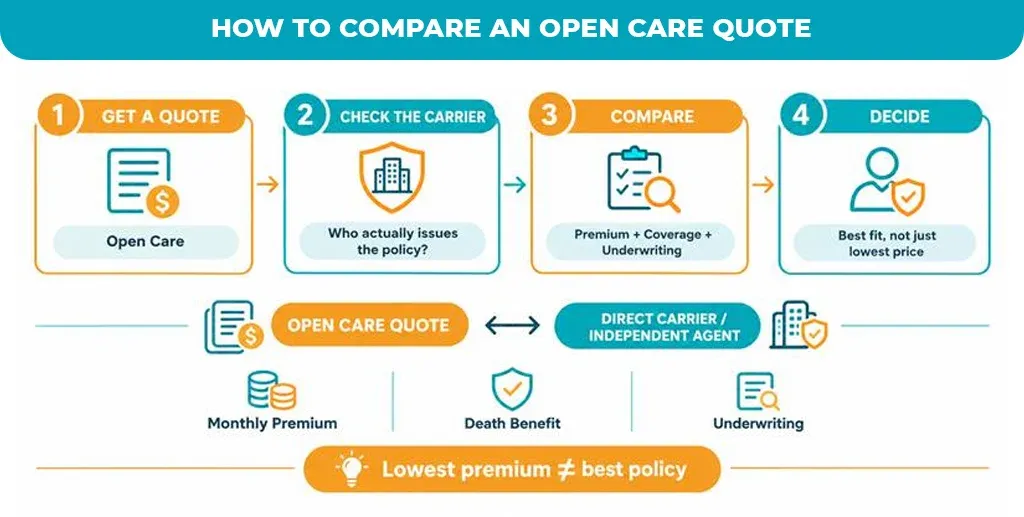
How to Compare an Open Care Quote 

Sizing the right amount of coverage is a useful independent check before comparing prices. According to the National Funeral Directors Association’s most recent General Price List study, the median cost of a funeral with viewing and burial is $8,300, while a funeral involving cremation runs a median of $6,280. Matching your final expense coverage amount to your region’s typical funeral cost, rather than to whatever round number sounds appealing in an ad, is a more reliable way to choose a death benefit than anchoring on a teaser price.

The most direct way to know whether an Open Care quote is competitive is to request pricing from at least one other source, either a direct carrier such as Mutual of Omaha or Aetna, or an independent agent who represents several A-rated companies side by side, and compare both the monthly premium and the underwriting path (Simplified Issue versus Guaranteed Issue) before deciding.

Conclusion

Navigating final expense coverage requires looking past headline teasers to find a transparent policy that matches your actual needs and budget. Open Care Life Insurance offers accessible entry points for seniors, but its broker status and hidden carrier partnerships make comparing independent options essential before signing any paperwork. 

When evaluating your final expense options, always prioritize verified financial strength, clear underwriting terms, and fixed monthly premiums that won’t surprise you later. To stop guessing with your family’s financial security, secure a custom, side-by-side market comparison from a trusted independent source. Premier Services Agency shops top-rated, A-rated carriers directly for you so you know the exact underwriting company behind your policy. Visit Premier Services Agency to get a quote and get your free personalized quote today.
Frequently Asked Questions (FAQs)

Yes. Open Care is a licensed insurance agency authorized to sell insurance, and the policies it places come from real, regulated carriers. It is not accredited by the Better Business Bureau and does not carry its own A.M. Best rating, since brokers generally do not; the rating that matters is the underlying carrier's.

It depends heavily on age, health, gender, smoking status, and coverage amount. The advertised $7.49-a-month rate applies only to a $2,000 policy for a healthy, non-smoking 50-year-old woman. A more typical $8,000 policy runs roughly $17 to $60 a month for non-smokers in their 40s through 60s, and considerably more for applicants in their 80s or 90s or on Guaranteed Issue plans.

Open Care does not publish a complete list of its partner carriers on its website or in its commercials. Industry reviewers have confirmed Mutual of Omaha as at least one underwriting partner, since Open Care's own online final expense application routes to a Mutual of Omaha product. Other carrier partnerships have not been independently verified.

It depends on the underwriting path. Simplified Issue final expense plans have no waiting period once approved. Guaranteed Issue plans carry a two-year graded period, during which a death from natural causes pays out only a refund of premiums plus interest rather than the full face amount; accidental death is typically covered at 100% from day one on both plan types.

Independent reviews cite a lack of transparency about the underwriting carrier and a high volume of follow-up marketing calls and mailers after a quote request as the most consistently reported issues, rather than disputes over claims payment. Because there are very few public reviews under Open Care's name, it is difficult to independently confirm the frequency of any specific complaint type.