
A long term care insurance quote depends on more than your age. The benefit amount, the length of coverage, inflation protection, the waiting period before benefits start, and whether you choose a traditional or hybrid policy can change the price by thousands of dollars a year.
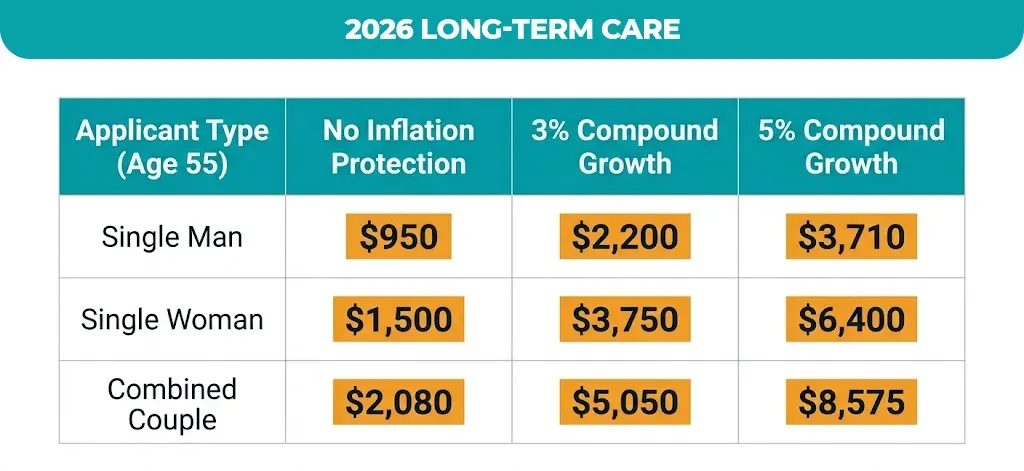
Quick answer: A traditional long-term care policy with $165,000 in initial benefits costs about $950 a year for a healthy 55-year-old man and $1,500 for a woman, or $2,200 and $3,750 with 3% compound inflation growth (AALTCI 2026). Hybrid life/LTC policies cost more but lock in premiums and pay a death benefit if you never need care.
How does a long term care insurance quote work?
Long-term care insurance pays for help with daily living, at home, in assisted living, or in a nursing home, when you can’t perform basic activities on your own or have severe cognitive impairment. Your quote is based on your age, health, the benefits you choose, and the policy type. Buying in your 50s usually means lower premiums and better odds of qualifying.
The real cost of long-term care
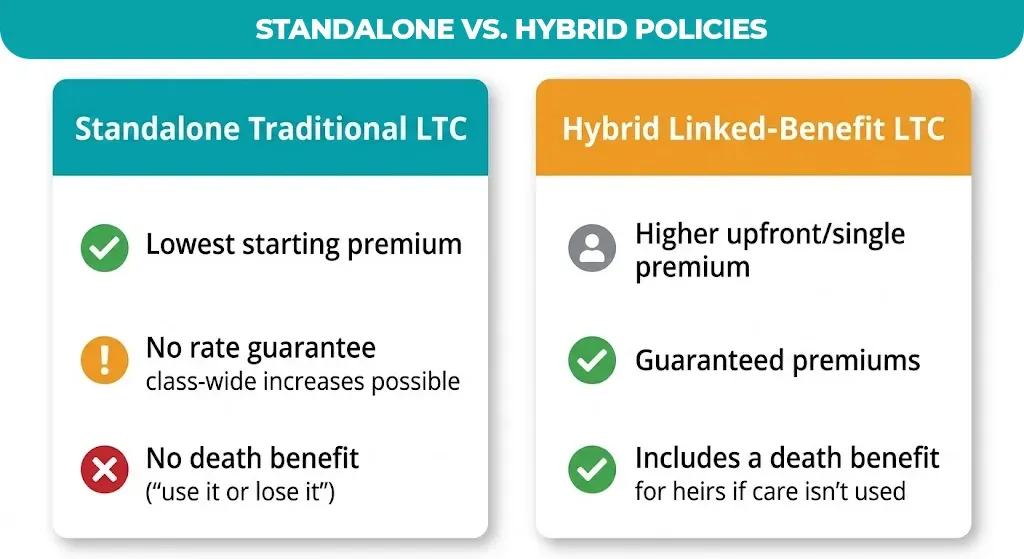
CareScout’s 2025 Cost of Care Survey (released March 2026) shows why many families plan ahead:
| Type of care | 2025 national median annual cost |
| Non-medical in-home caregiver | $80,080 |
| Adult day health care | $24,700 |
| Assisted living community | $74,400 |
| Nursing home, semi-private room | $114,975 |
| Nursing home, private room | $129,575 |
Medicare generally doesn’t pay for long-term custodial care, and Medicaid covers it only after you’ve spent down most of your assets. Without coverage, these costs often come from retirement savings.
The 6 activities of daily living and benefit triggers
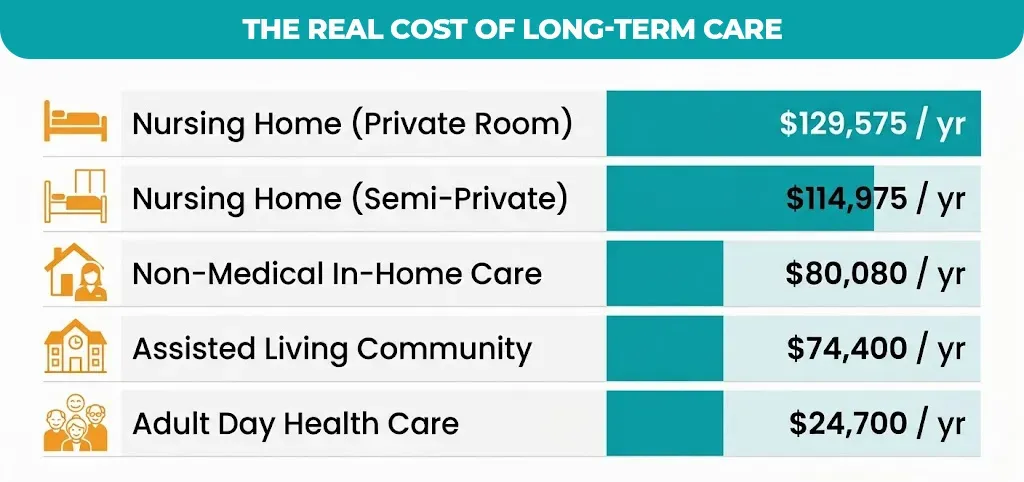
Tax-qualified policies follow federal rules (IRC §7702B). Benefits begin when a licensed health care practitioner certifies that you either:
• Can’t perform at least 2 of the 6 activities of daily living (ADLs) without substantial help, for a period expected to last at least 90 days, or
• Need substantial supervision because of severe cognitive impairment, such as Alzheimer’s disease or another dementia.
The six ADLs are bathing, dressing, eating, toileting, transferring (moving in and out of a bed or chair), and continence.
Note: After you qualify, most policies also have an elimination period, a waiting period you pay for yourself before benefits begin. More on that below.
See Premier Services Agency’s long-term care insurance page for an overview.
Standalone vs. hybrid long-term care insurance quotes
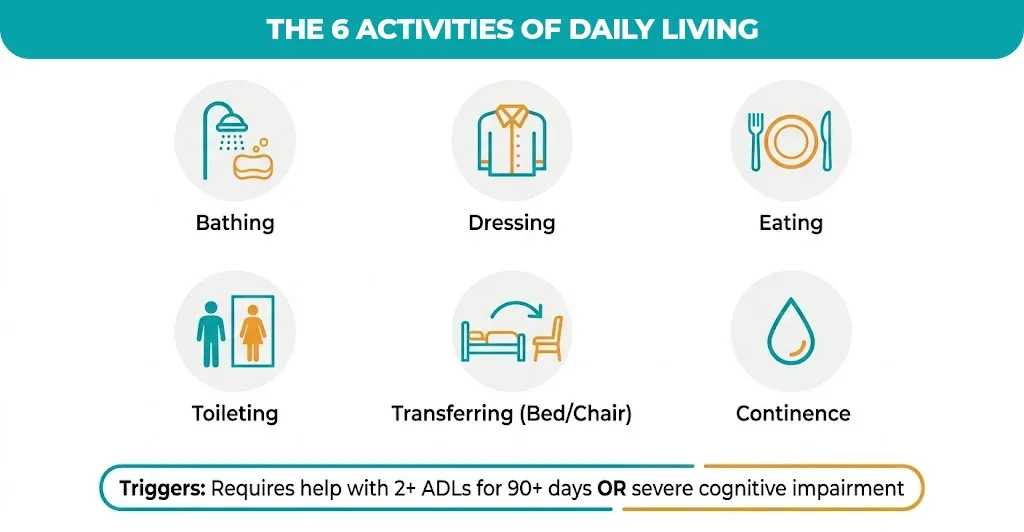
Traditional standalone LTC insurance gives the most care coverage for the lowest starting premium, but premiums can rise and there’s no payout if you never need care. Hybrid (linked-benefit) policies combine life insurance or an annuity with LTC benefits, usually with guaranteed premiums and a death benefit for heirs. They cost more upfront.
Standalone traditional LTC policies
A standalone policy pays only for long-term care. You choose a monthly benefit, a benefit period or total pool, an elimination period, and inflation protection. Premiums aren’t guaranteed: insurers can ask state regulators to approve increases for a whole class of policyholders, which has happened often with older policies. If you never need care, the premiums aren’t returned (“use it or lose it”). Examples include Mutual of Omaha’s MutualCare policies and Northwestern Mutual’s QuietCare.
Hybrid linked-benefit policies
A hybrid policy is usually a universal or whole life policy (or an annuity) with an LTC benefit built in. If you need care, you draw from the LTC benefit; if you don’t, your heirs receive a death benefit. Many hybrids allow a single premium or a fixed number of payments with guaranteed rates. Examples include Nationwide’s CareMatters II and New York Life’s Asset Flex.
Hybrid policies pay benefits in one of two ways:
• Reimbursement: Pays actual qualified care costs, up to your monthly limit, with receipts.
• Cash indemnity: Pays your full monthly benefit once you qualify, regardless of actual costs. Nationwide’s CareMatters II, for example, pays cash benefits.
See Premier Services Agency’s permanent life insurance and indexed universal life pages for how the life insurance side works.
Standalone LTC vs. hybrid linked-benefit LTC
| Feature | Standalone traditional LTC | Hybrid linked-benefit LTC |
| Premium guarantee | No; class-wide increases possible | Usually guaranteed |
| Death benefit | None | Yes, if LTC benefits aren’t fully used |
| Rate hike risk | Yes | Low |
| Inflation protection | 3% or 5% compound options common | Available on many policies, at extra cost |
| Starting cost | Lowest | Higher; often a large single or limited-pay premium |
| Ideal buyer | Wants maximum care coverage for the lowest premium | Has savings to reposition; wants guarantees and a legacy |
AALTCI’s 2026 comparison for a 55-year-old shows the gap: a traditional policy with a $180,000 benefit pool costs about $1,050 a year for a man and $1,645 for a woman. Two sample hybrid policies cost about 3,265–3,750 a year, with 180,000–240,000 in LTC benefits and a $120,000 minimum death benefit.
Key variables that affect your long term care insurance quote
Your age and health set the baseline. Your benefit choices then drive most of the price: the monthly benefit, how long benefits last, inflation protection, and the elimination period. Couples can often save with spousal discounts.
Age and health
Premiums rise with each year of age, and health conditions can lead to higher rates or a decline. Many insurers decline applicants with existing dementia, recent strokes, or conditions that already require help with daily activities. Applying while healthy, often in your 50s or early 60s, gives you the most choice.
Monthly benefit and benefit period
You choose how much the policy pays per month and for how long (or a total benefit pool). Carrier ranges are wide: Mutual of Omaha offers 1,500–10,000 a month, Northwestern Mutual 1,500–12,000, and Nationwide’s CareMatters 2,500–20,833, with benefit periods commonly from two to seven years. Compare your benefit with local care costs, such as the $74,400 national median for assisted living (about $6,200 a month).
Inflation protection
Care costs keep rising, so inflation protection is one of the most important choices. With 3% compound growth, a $165,000 pool grows each year; 5% compound grows faster but costs much more. AALTCI’s 2026 index shows the effect for a 55-year-old man: $950 a year with no growth, $2,200 with 3%, and $3,710 with 5%.
Elimination period and couples discounts
The elimination period is the number of days you pay for care yourself before benefits begin; 90 days is common, and Nationwide’s CareMatters uses a 90-day elimination period. A longer period lowers your premium. Couples often save: Mutual of Omaha offers 15% for insured couples, and Northwestern Mutual offers up to 30% if both partners are approved.
2026 annual premium benchmarks
AALTCI 2026 Price Index, $165,000 initial benefit, select health, Illinois pricing:
| Applicant (age 55) | No inflation growth | 3% compound growth | 5% compound growth |
| Single man | $950 | $2,200 | $3,710 |
| Single woman | $1,500 | $3,750 | $6,400 |
| Couple, combined | $2,080 | $5,050 | $8,575 |
AALTCI also reports:
• Single woman, age 60: about $4,450 a year on average for $165,000 in benefits
• Couple, both 60, 3% growth: $4,591 to $7,173 a year combined, depending on the insurer
• Couple, both 65, 3% growth: about $7,030 a year
Note: AALTCI doesn’t publish a full age 50–65 grid for singles, so the table shows age 55 only. Women pay more than men because they’re more likely to need care, and for longer. Prices vary by state and health class.
State-specific LTC quotes and Partnership programs
Long-term care premiums and rules vary by state. Many states run Long-Term Care Partnership programs: if you buy a qualifying Partnership policy and later need Medicaid, you can keep assets equal to the benefits your policy paid. That protection is called dollar-for-dollar asset disregard.
Texas long term care insurance quotes and the Partnership
Texas created its Long-Term Care Partnership program under Senate Bill 22 (80th Legislature), effective March 1, 2008. The program is part of Medicaid, run by the Health and Human Services Commission with the Texas Department of Insurance. If you use a Partnership policy, assets equal to the benefits it paid aren’t counted for Medicaid eligibility and are protected from estate recovery. The law also allows reciprocity with other Partnership states, and agents selling these policies must complete training.
Missouri long term care insurance quotes and regional costs
Missouri’s Medicaid eligibility manual includes a Missouri Long Term Care Partnership Program section (1030.055.00). Care costs vary widely by region, so match your monthly benefit to prices where you expect to receive care, whether that’s St. Louis, Kansas City, or a rural area. Check local CareScout costs for your city before choosing a benefit amount.
California long term care insurance quotes and AB 567
California runs the California Partnership for Long-Term Care through the Department of Health Care Services, with Partnership policies that include Medi-Cal asset protection. California’s AB 567 (2019) created a Long-Term Care Insurance Task Force to study a statewide program, which the task force recommended funding with a payroll tax. As of the most recent updates available (early 2024), no statewide program or payroll tax had been enacted, and no bill had been introduced. Check for new legislation before making decisions based on a possible opt-out.
Group long-term care insurance quotes and plans
Some employers and associations offer group long-term care insurance quotes and plans, sometimes with simplified underwriting during enrollment. Group plans can be convenient, but compare them with individual quotes: portability, inflation options, and premium guarantees vary.
| State | Partnership program | Key note |
| Texas | Yes (since 2008) | Dollar-for-dollar asset disregard; reciprocity allowed |
| Missouri | Yes (Medicaid manual section 1030.055.00) | Size benefits to local care costs |
| California | Yes (California Partnership) | No statewide payroll tax enacted as of early 2024 |
Note: Partnership rules, including inflation protection requirements by age, vary by state. Ask your agent whether a policy is Partnership-qualified in your state.
Carrier review and expert recommendations
There’s no single cheapest or best long-term care insurer for everyone. Prices for the same coverage can differ by thousands of dollars between carriers, and the best fit depends on whether you want a standalone or hybrid policy, coverage for a couple, or cash benefits. Experts like Suze Orman and Dave Ramsey both support planning for long-term care, with different emphases.
Who has the cheapest long-term care insurance?
It depends on your age, health, state, and benefits. AALTCI’s 2026 survey found that a 60-year-old couple buying similar 3% growth coverage could pay anywhere from $4,591 to $7,173 a year depending on the insurer, more than a 50% difference. Getting quotes from several carriers is the only reliable way to find the cheapest option for you.
Best long-term care insurance companies by category
| Category | Carrier | Why |
| Standalone LTC | Mutual of Omaha | MutualCare policies, 1,500–10,000 monthly benefits, stackable discounts |
| Hybrid / customization | Nationwide | CareMatters II (cash benefits) and CareMatters Together (shared couples pool) |
| Financial stability | New York Life | Top financial strength ratings; Secure Care and Asset Flex hybrid |
| Couples | Northwestern Mutual | QuietCare with up to 30% spousal discount and survivorship rider |
This list follows Money.com’s October 2026 rankings. Money.com also gives honorable mentions to OneAmerica and National Guardian Life. If you’re searching for an AARP long term care insurance quote or a Genworth long term care insurance quote, ask which carrier currently underwrites any AARP-endorsed plan and whether Genworth is writing new policies in your state, since availability changes.
Who does Suze Orman recommend for long-term care insurance?
Suze Orman doesn’t endorse a single company. She has called herself “a big believer in the value of long-term care insurance” and recommends that “once you turn 50 you research whether a LTCi policy makes sense.” Her practical advice:
• Plan for inflation; don’t drop the inflation rider to save money.
• Buy “a policy where you could absorb a doubling in the premium cost.”
• Don’t drop a policy after paying for 10 or 15 years because of a rate increase; talk with family about sharing the cost instead.
What does Dave Ramsey say about long-term care insurance?
Ramsey Solutions recommends long-term care insurance for people nearing retirement age, and its summary answer to who needs it is “anyone over 60.” It says to buy while you’re still healthy, but only after you’re debt-free with an emergency fund. It calls coverage “a must” if you want to age at home, and warns that care costs can “wipe out your savings.”
| Expert | When to start | Key point |
| Suze Orman | Research at 50 | Keep inflation protection; buy a premium you could afford if it doubled |
| Dave Ramsey | Around 60 / nearing retirement | Be debt-free with an emergency fund first; buy while healthy |
What is the best insurance company for long-term care?
The best company is the one that offers the coverage you need, at a price you can keep paying, with strong financial ratings. For guarantees and a death benefit, look at hybrid carriers like Nationwide or New York Life; for maximum care coverage per dollar, standalone carriers like Mutual of Omaha; for couples, Northwestern Mutual. An independent agency can compare these side by side.
How to get an online long term care insurance quote
The fastest way to get useful long-term care insurance quotes online is to estimate your care gap first, pick a policy type, then compare several carriers through an independent agency. A short health pre-screen before you apply avoids surprises.
Step 1: Estimate your monthly care gap
Use a long term care insurance quote calculator approach:
Monthly care gap = Expected monthly cost of care in your area
– Monthly income available for care (Social Security, pension, other)
For example (illustrative), if assisted living near you costs about $6,200 a month and you could put $2,500 of income toward it, your gap is about $3,700 a month. That’s a starting point for your monthly benefit.
Step 2: Choose standalone or hybrid
• Want the most coverage for the lowest premium? Start with standalone quotes.
• Want guaranteed premiums and money left to heirs if you never need care? Ask for hybrid quotes.
• Not sure? Compare both for the same benefit amount.
Step 3: Request multi-carrier quotes
Ask for quotes with the same monthly benefit, benefit period, elimination period, and inflation option across carriers so you’re comparing like with like. Include couples quotes if you’re married.
Step 4: Complete a health pre-screen
Share your medications, diagnoses, and recent treatment with the agent before applying. A pre-screen tells you which carriers are likely to approve you, so you don’t collect a decline on your record.
Note: An instant online quote is an estimate. Your final premium is set after underwriting, which may include a health interview, medical records, or a cognitive screening.
Conclusion:
Long-term care can cost $74,000 to $130,000 a year, and planning ahead protects both your savings and your children. The right long term care insurance quote balances enough benefits, real inflation protection, and a premium you can keep paying for decades.
| Your situation | Best starting point |
| Age 50–60, healthy, want lowest premium | Standalone policy with 3% compound inflation |
| Have savings to reposition, want guarantees | Hybrid life/LTC policy |
| Married couple | Couples discount or shared-pool policy |
| Worried about rate increases | Hybrid with guaranteed premiums |
| May rely on Medicaid later | Partnership-qualified policy in your state |
| California resident | Watch for any future state program; consider a Partnership policy |
Compare LTC quotes at Premier Services Agency
Premier Services Agency helps individuals and couples across the United States compare long-term care options, including traditional and hybrid policies, so you can choose coverage that fits your budget and goals. Premier Services Agency long-term care specialists can help you line up comparable quotes and check whether a policy qualifies for your state’s Partnership program.
Get a long-term care insurance quote on Premier Services Agency.